
Market Climbs from USD 2.21 Billion in 2026 at a 21.64% CAGR: North America Leads, Asia-Pacific Is the Fastest-Growing Region and AAV Vectors Hold the Largest Type Share
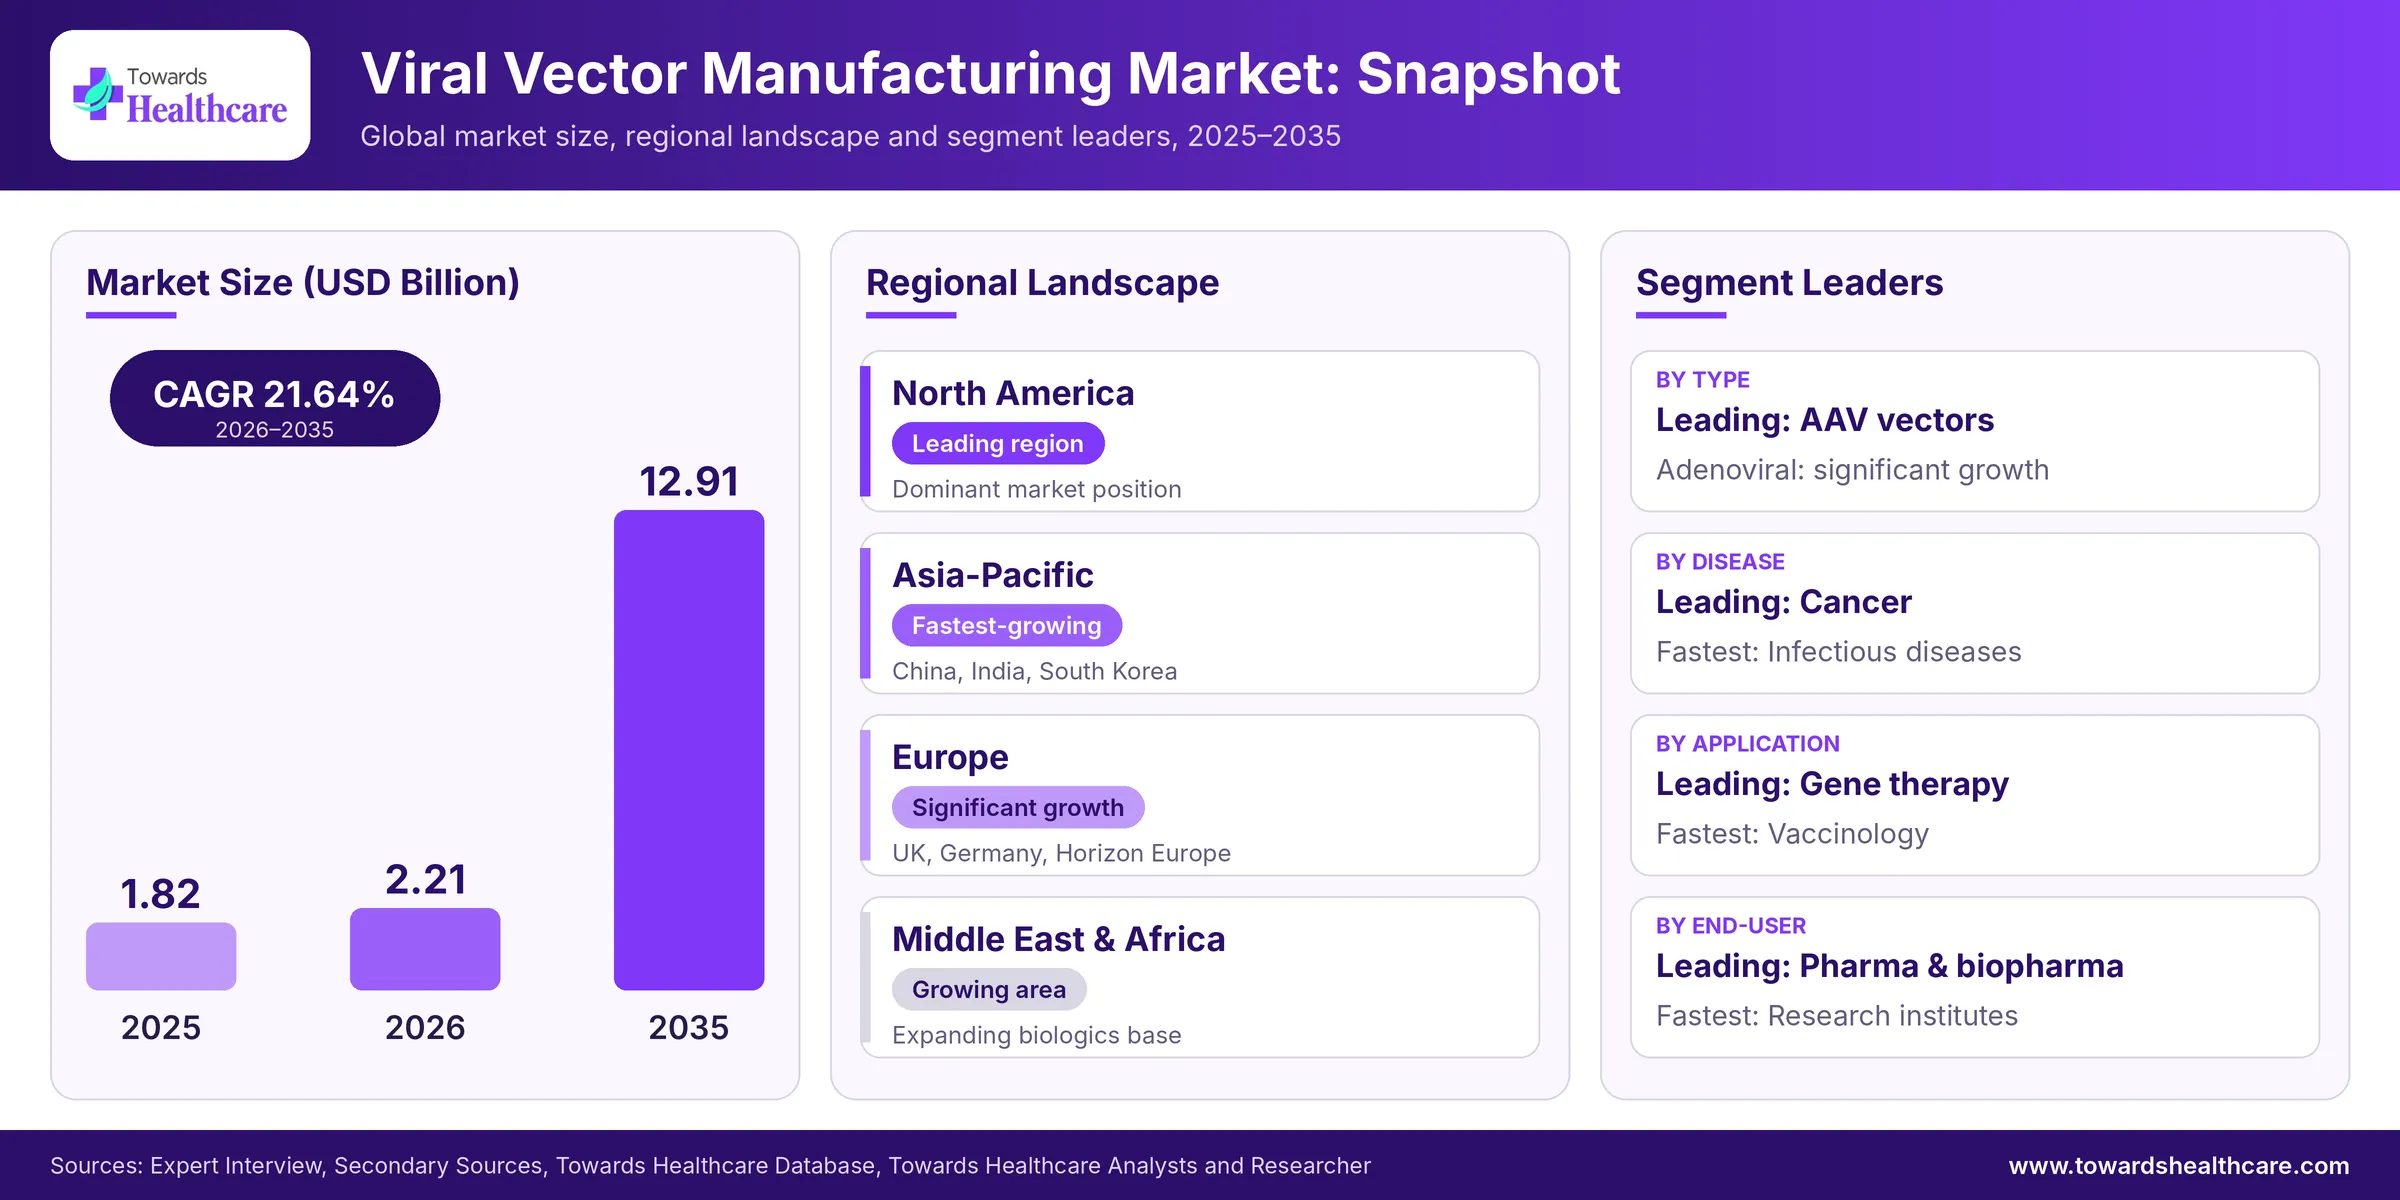
Ottawa, Nov. 17, 2026 (GLOBE NEWSWIRE) -- Viral vector manufacturing, the upstream production, downstream purification and quality control of engineered, replication-deficient viruses that deliver genetic material into cells, now sits at the center of cell and gene therapy pipelines, vaccines and advanced biopharmaceuticals. Towards Healthcare, a sister firm of Precedence Research, estimates the global market at USD 2.21 billion in 2026 and forecasts USD 12.91 billion by 2035, an absolute increase of USD 10.70 billion in nine years.
The 2026 evidence points in two directions at once. FDA’s Center for Biologics Evaluation and Research finalized CMC flexibilities for cell and gene therapy license applications on 5 May 2026, REGENXBIO is preparing a Duchenne muscular dystrophy BLA for the first quarter of 2027, and Oxford Biomedica (OXB) signed a record 17 new clients in the first half. Yet VintaBio, a Philadelphia viral vector and vaccine manufacturer, made an assignment for the benefit of creditors on 27 October 2026, and OXB lowered its 2026 revenue guidance to £180–200 million as clients shifted order timing.
For executives, the question is no longer whether demand exists. It is which vector types, sites and partners will carry commercial volume, how much capacity is worth committing, and where across North America, Europe and Asia-Pacific that capacity will earn its return.
Request a sample: https://www.towardshealthcare.com/sample/5631
Market Size and Growth
| Market Indicator | Value | |
| Market size, 2025 (base year) | USD 1.82 billion | |
| Market size, 2026 | USD 2.21 billion | |
| Forecast market size, 2035 | USD 12.91 billion | |
| CAGR, 2026–2035 | 21.64 | % |
| Absolute growth, 2026–2035 (calculated) | USD 10.70 billion | |
| Leading region | North America | |
| Fastest-growing region | Asia-Pacific | |
| Leading type / disease | Adeno-associated viral (AAV) vectors / Cancer | |
| Leading application / end-user | Gene therapy / Pharmaceutical and biopharmaceutical companies | |
| Report code / last updated | 5631 / 20 August 2026 | |
Figure 1: Viral vector manufacturing market snapshot, 2025–2035
Growth rests on the rising prevalence of genetic disorders and cancers, larger gene therapy clinical pipelines and a steady run of regulatory approvals. On the supply side, suspension-based production, single-use systems, process automation and advanced purification are improving consistency and scalability, while pharmaceutical sponsors keep committing capital to advanced therapies.
Sources: Expert Interview, Secondary Sources, Towards Healthcare Database, Towards Healthcare Analysts and Researcher
Segment Intelligence: Dominant and Fastest-Growing Segments
| Segment Group | Leading | Fastest-Growing | Why It Matters |
| Type | AAV vectors (largest share, 2024) | Adenoviral vectors (significant growth, 2024) | AAV pipelines set the demand for specialized capacity; adenoviral vectors serve vaccines and oncology |
| Disease | Cancer | Infectious diseases | Oncology anchors current volume; vaccines open a second demand curve |
| Application | Gene therapy | Vaccinology | Gene therapy drives commercial-scale supply; vaccine platforms favor scalable processes |
| End-user | Pharmaceutical and biopharmaceutical companies | Research institutes | Sponsors buy scale; institutes buy clinical-grade vector for early programs |
Figure 2: Leading and fastest-growing segments
By type, AAV vectors held the largest share in 2024 on a favorable safety profile, long-term gene expression and a growing pipeline of AAV-based therapies that has pulled specialized infrastructure into place. Adenoviral vectors also posted significant growth, backed by high transduction efficiency; in a 2024 clinical trial, the oncolytic adenovirus TILT-123 showed safety and tumor-targeting promise in advanced solid cancers.
By disease, cancer led in 2024 as CAR-T and oncolytic virus-based treatments expanded alongside oncology R&D. Infectious diseases are expected to grow fastest on demand for new vaccines against HIV, malaria and tuberculosis and on better molecular diagnostics and surveillance. An estimated 2 million new U.S. cancer diagnoses in 2024 keep oncology demand visible.
By application, gene therapy accounted for the highest share in 2024 as AAV advances improved delivery efficiency and approvals accelerated vector demand. Vaccinology is projected to grow fastest, helped by new platforms, more scalable production and public research support.
By end-user, pharmaceutical and biopharmaceutical companies led in 2024 by expanding in-house capacity, forming collaborations and scaling for commercial supply. Research institutes are estimated to grow fastest as public and private funding and academia-industry links lift demand for specialized tools.
Sources: Expert Interview, Secondary Sources, Towards Healthcare Database, Towards Healthcare Analysts and Researcher
Regional and Country Analysis
| Region | Position | Country Signals |
| North America | Leading region | U.S. and Canada |
| Asia-Pacific | Fastest-growing region | China, India, South Korea |
| Europe | Significant growth expected | UK, Germany |
| Middle East & Africa | Growing area | South Africa |
| Latin America | Covered in the report | Brazil, Mexico, Argentina |
North America led in 2024 on biopharmaceutical infrastructure, gene therapy investment and supportive regulation. In the U.S., FDA’s CBER set out a flexible approach to CMC for cell and gene therapies on 11 January 2026 and finalized guidance on 5 May. REGENXBIO reported USD 251.0 million in cash at 30 September 2026 and a pre-BLA meeting planned for the fourth quarter. The VintaBio asset sale, with bids due 15 December 2026, shows the other side of the cycle. In Canada, Virica Biotech and FUJIFILM Biosciences began an AAV yield collaboration on 8 April 2026 under a National Research Council program.
Asia-Pacific is expected to grow fastest on biotechnology investment, rising gene therapy demand and cost-effective manufacturing. In China, Porton Advanced received an NMPA Class C drug manufacturing license on 5 August 2026, which allows commercial contract manufacturing of cell and gene therapy products. In India, Nucelion Therapeutics, a Bharat Biotech subsidiary, agreed on 21 October 2026 to manufacture VeGen Bio’s dual-target CAR-T candidate, building on Bharat Biotech’s 50,000-square-foot cell and gene therapy and viral vector site at Genome Valley.
Europe benefits from Horizon Europe’s EUR 11.5 billion research allocation and more than EUR 1 billion from InvestEU for biotechnology and medicine projects. In the UK, OXB reported first-half 2026 revenue of £79.8 million, up 9%, and brought its Durham, North Carolina site online. In Germany, ProBioGen’s Berlin facility received extended GMP authorization on 10 November 2026 covering viral vectors, viral vaccines and advanced therapy medicinal products. Merck KGaA reported Q3 2026 net sales of EUR 5.6 billion, up 5.1% organically, with Process Solutions the main growth driver.
Middle East & Africa is growing on expanding biologics infrastructure and rising chronic and infectious disease burden. The report counts 11 viral vector manufacturers across Africa, 10 of them with operational formulation, fill and finish capacity.
What Is Changing in the Industry
1. Regulators ease the path to licensure
On 11 January 2026, FDA’s CBER published its flexible approach to CMC for cell and gene therapies, and on 5 May 2026 it finalized guidance on CMC flexibilities for biologics license applications. Sponsors gain room on product specifications and validation approach, particularly for small patient populations. A mid-2026 draft guidance extended platform-data leveraging to genome-editing products.
What it indicates: Process immaturity is a smaller barrier to filing, but a defensible control strategy still decides outcomes, which favors partners with strong analytics and comparability experience.
2. Capacity reset begins
VintaBio, a purpose-built cGMP viral vector and vaccine manufacturer with demonstrated AAV8 production, made an assignment for the benefit of creditors on 27 October 2026. Its assignee is accepting bids for the facility, equipment and know-how until 5:00 p.m. ET on 15 December 2026.
What it indicates: Installed capacity is not the same as usable capacity. Buyers can acquire ready sites at lower cost, while sponsors should test partner balance sheets alongside technical fit.
3. CDMO demand builds, but order timing is lumpy
OXB reported H1 2026 revenue of £79.8 million, up 9%, with 17 new clients, 59 active programs, a USD 730 million new-business pipeline up 30% and a revenue backlog of about £193 million. Full-year revenue guidance now stands at £180–200 million, down from the £220–240 million issued with 2025 results. OXB also signed a commercial supply agreement with Bristol Myers Squibb for lentiviral vectors supporting its CAR-T portfolio.
What it indicates: Late-stage and commercial programs are arriving, yet revenue follows client decisions rather than capacity, so forecasts need program-level visibility.
4. Scale CDMOs consolidate their position
Lonza reported H1 2026 sales of CHF 3.4 billion, up 16% at constant exchange rates, and on 14 October 2026 held its Capital Markets Day at the Vacaville, California biologics site it bought from Roche in 2024. It confirmed a full-year outlook of 11–12% CER sales growth and a CORE EBITDA margin of 33–34%.
What it indicates: Integrated, pure-play CDMO platforms are converting acquired capacity into margin, raising the bar for smaller providers.
5. Regional manufacturing nodes widen
Porton Advanced’s NMPA license in China and Nucelion’s CAR-T manufacturing agreement in India, both in the second half of 2026, add commercial-stage and cost-competitive options outside the U.S. and Europe.
What it indicates: Sponsors can dual-source across regions, which pressures pricing and lengthens the list of qualified suppliers.
Key Market Drivers
- Genetic disorders and cancer: Rising prevalence sustains demand for AAV and lentiviral delivery in precision therapies.
- Maturing pipelines: REGENXBIO’s RGX-202 BLA is on track for the first quarter of 2027, and Novartis began U.S. sales of ITVISMA in the first quarter of 2026.
- Regulatory flexibility: FDA’s January and May 2026 CMC actions reduce filing friction for cell and gene therapies.
- Process innovation: Suspension-based production, single-use systems, automation and continuous processing raise yield and consistency.
- Public and private investment: Horizon Europe, InvestEU and Canadian innovation funding support capacity and research.
Major Challenges
- Complex production: Strict quality standards, long approval timelines and high facility costs raise entry barriers.
- Capacity mismatches: The VintaBio assignment shows that specialized sites can fail when utilization lags.
- Order-timing risk: OXB’s revised 2026 guidance reflects client ordering shifts rather than lost demand.
- Skills and technology transfer: Limited specialist talent slows scale-up and site-to-site transfer.
- Safety setbacks: REGENXBIO’s RGX-121 Hunter syndrome program is under a clinical hold, which has moved its targeted BLA resubmission.
Emerging Opportunities
- Vaccine platforms: Vaccinology is the fastest-growing application, and ProBioGen’s Berlin authorization targets sterile viral drug substance.
- Yield and cost gains: The FUJIFILM Biosciences–Virica collaboration pairs HEK293 media with enhancers to lift AAV productivity.
- Capacity acquisition: Ready cGMP sites such as VintaBio’s let buyers shorten timelines and reduce capital outlay.
- Regional hubs: China and India are adding commercial-grade and cost-competitive vector capacity.
- Research-institute demand: The fastest-growing end-user group needs clinical-grade vector for early programs.
Company and Competitive Intelligence
The report names Merck KGaA, Lonza, BD, FUJIFILM Biotechnologies, Brammer Bio, Cell Therapy Catapult, Waisman Biomanufacturing, GENEZEN, Yposkesi and REGENXBIO among the leading participants. The field mixes CDMOs, tool and reagent suppliers and gene therapy developers with in-house plants, so competition runs on platform breadth, vector expertise and regulatory track record.
| Company | Role or Key Products | Latest Reported Data | Strategic Direction |
| Lonza | Global CDMO; integrated biologics | H1 2026 sales CHF 3.4 billion, up 16% CER; FY2026 outlook 11–12% CER growth | Completed pure-play CDMO shift; upgraded growth model on 14 Oct 2026 |
| OXB | Viral vector CDMO (lentiviral, AAV, adenoviral) | H1 2026 revenue £79.8 million, up 9%; backlog about £193 million | Durham, NC site online; ambition of about £500 million revenue by 2030 |
| Merck KGaA | Process Solutions; reagents; viral vector services | Q3 2026 net sales EUR 5.6 billion, up 5.1% organic | Integrated viral vector offer via the USD 600 million Mirus Bio acquisition |
| FUJIFILM Biotechnologies / Biosciences | CDMO; BalanCD HEK293 media | AAV enhancer collaboration with Virica announced 8 Apr 2026 | Media plus enhancers to lift AAV yield and cut cost of goods |
| REGENXBIO | AAV developer; in-house manufacturing center | Cash USD 251.0 million at 30 Sep 2026 | RGX-202 BLA planned for Q1 2027; sura-vec data due Q4 2026 |
| ProBioGen | Viral vector and vaccine CDMO, Berlin | Extended GMP authorization on 10 Nov 2026 | Sterile viral drug substance for vaccines and ATMPs |
| Porton Advanced | Cell and gene therapy CDMO | NMPA Class C license on 5 Aug 2026; 26 global INDs supported | Commercial-stage manufacturing from China |
| Nucelion Therapeutics | CGT CRDMO (Bharat Biotech) | VeGen Bio CAR-T agreement on 21 Oct 2026 | Local plasmid, vector and cell therapy production in India |
| VintaBio | AAV8 and vaccine CDMO, Philadelphia | Assignment for benefit of creditors on 27 Oct 2026 | Assets offered for sale; bids due 15 Dec 2026 |
Customer and Buyer Intelligence
| Target Account Group | Decision-Makers | Purchase Signals | Commercial Opportunity |
| AAV gene therapy developers | CMC and technical operations heads, COOs | BLA submissions, pre-BLA meetings, pivotal readouts | Commercial-scale AAV supply and process transfer |
| CAR-T and ex vivo cell therapy developers | Supply chain and procurement leaders | Commercial supply agreements, such as OXB with Bristol Myers Squibb | Long-term lentiviral vector supply |
| Vaccine developers and public programs | R&D heads, government program managers | Outbreak-response funding, GMP authorizations | Adenoviral and MVA vector production |
| Research institutes | Translational research directors | Public research funding, academia-industry collaboration | Clinical-grade vector for early trials |
| Pharmaceutical and biopharmaceutical sponsors | Corporate development and M&A teams | Asset sales, facility acquisitions | Buying or leasing installed capacity |
| Media, reagent and equipment buyers | Process development and procurement leads | Yield-improvement partnerships | Single-use systems, media and transfection reagents |
How Towards Healthcare Supports Decision-Making
Master Dataset. A single, structured view of the viral vector manufacturing market by type, disease, application, end-user and region, from the 2025 base year of USD 1.82 billion to the 2035 forecast of USD 12.91 billion. It helps planners size capacity, test scenarios and decide where to build, buy or partner.
Towards Healthcare Quadrant. A positioning view of vector manufacturers and suppliers. It helps sponsors shortlist CDMOs by platform breadth and regulatory readiness, and helps providers see where rivals are consolidating.
Interactive Intelligence Dashboard. Live filtering of segments, regions and company moves, such as facility sales, license awards and earnings. It supports timing decisions on supplier outreach and investment.
Quality & Manufacturing Intelligence. Coverage of GMP authorizations, CMC guidance and process trends, including suspension production, single-use systems and yield enhancers. It informs technology transfer, comparability planning and supplier audits.
Customized Research. Tailored analysis, for example AAV versus lentiviral capacity in a chosen region or an acquisition screen for available cGMP sites. It supports board-level build, buy and partner choices.
| Solution | What It Provides | How It Helps |
| Master Dataset | Segment, regional and company data for 2025–2035 | Sizing, forecasting and scenario planning |
| Towards Healthcare Quadrant | Competitive positioning of providers | Partner shortlisting and benchmarking |
| Interactive Intelligence Dashboard | Filterable, current market views | Faster monitoring and timing decisions |
| Quality & Manufacturing Intelligence | Regulatory, GMP and process insight | Lower tech-transfer and compliance risk |
| Customized Research | Bespoke studies on a stated question | Investment, M&A and sourcing decisions |
Why Continuously Updated Intelligence Matters
This market moves on short and long clocks. Monthly tracking catches regulatory actions, GMP authorizations and facility sales, such as ProBioGen’s November update and the VintaBio process. Quarterly cycles bring earnings and pipeline milestones, including REGENXBIO’s Q3 report and Lonza’s Q3 update. Six-monthly reviews align with half-year results, such as OXB’s H1 report, and with contract renewals. Annual refreshes reset forecasts, guidance and capital plans, which matters most when guidance is revised mid-year.
Strategic Outlook
- CEOs and CXOs: With the 2026 market at USD 2.21 billion and growing at 21.64% a year, choose capacity partners by balance-sheet strength as well as technology.
- Strategy and Business Development: Screen distressed or underused cGMP assets, since the VintaBio process invites bids until 15 December 2026.
- R&D: Use FDA’s May 2026 CMC flexibilities to plan phase-appropriate control strategies early, particularly for AAV programs.
- Procurement: Dual-source across regions as China and India add licensed and cost-competitive capacity.
- Investors: Track order conversion, backlog and utilization, because OXB shows demand and revenue timing can diverge.
- Manufacturers and Suppliers: Pair media, enhancers and single-use systems with yield claims, as the FUJIFILM–Virica collaboration does for AAV.
Company Ecosystem
Figure 3: Viral vector manufacturing company ecosystem
Call to Action
Decision-makers who need segment, regional and company detail behind these figures can use the full report and the options below.
- Report: https://www.towardshealthcare.com/insights/viral-vector-manufacturing-market-sizing
- Request a sample: https://www.towardshealthcare.com/sample/5631
- Checkout: https://www.towardshealthcare.com/checkout/5631
- Schedule a meeting: https://www.towardshealthcare.com/schedule-meeting
Fill out the form for relevant samples, case studies, and examples. sales@towardshealthcare.com
Related Reports
- Cell and Gene Therapy Market: https://www.towardshealthcare.com/insights/cell-and-gene-therapy-market
- Cell and Gene Therapy Manufacturing Market: https://www.towardshealthcare.com/insights/cell-and-gene-therapy-manufacturing-market-experiencing-significant-growth
- Cell and Gene Therapy Services Market: https://www.towardshealthcare.com/insights/cell-and-gene-therapy-services-market-sizing
- U.S. Cell and Gene Therapy CDMO Market: https://www.towardshealthcare.com/insights/us-cell-and-gene-therapy-cdmo-market-sizing
- U.S. Cell and Gene Therapy Market: https://www.towardshealthcare.com/insights/us-cell-and-gene-therapy-market-sizing
- North America Cell and Gene Therapy Market: https://www.towardshealthcare.com/insights/north-america-cell-and-gene-therapy-market-sizing
- Cell and Gene Therapy for Oncology Market: https://www.towardshealthcare.com/insights/cell-and-gene-therapy-for-oncology-market-sizing
- U.S. Plasmid DNA Contract Manufacturing Market: https://www.towardshealthcare.com/insights/us-plasmid-dna-contract-manufacturing-market-sizing
- Cell Therapy Monitoring Kits Market: https://www.towardshealthcare.com/insights/cell-therapy-monitoring-kits-market-sizing
- Cell and Gene Therapy Thawing Equipment Market: https://www.towardshealthcare.com/insights/cell-and-gene-therapy-thawing-equipment-market-sizing
- Single Use Bioprocessing Probes Sensors Market: https://www.towardshealthcare.com/insights/single-use-bioprocessing-probes-sensors-market-sizing
- U.S. Restricted Access Barrier System Market: https://www.towardshealthcare.com/insights/us-restricted-access-barrier-system-market-sizing
- Biopharmaceuticals Market: https://www.towardshealthcare.com/insights/biopharmaceuticals-market-is-rising-rapidly
- Biotechnology Market: https://www.towardshealthcare.com/insights/biotechnology-market
- Pharmaceutical Market: https://www.towardshealthcare.com/insights/pharmaceutical-market-sizing
- Molecular Diagnostics Market: https://www.towardshealthcare.com/insights/molecular-diagnostics-market-sizing
- Advanced Cancer Diagnostics Market: https://www.towardshealthcare.com/insights/advanced-cancer-diagnostics-market-sizing
- Medical Device CMO and CDMO Market: https://www.towardshealthcare.com/insights/medical-device-cmo-and-cdmo-market-sizing
- AI in Life Sciences Market: https://www.towardshealthcare.com/insights/ai-in-life-sciences-market
- Bioinformatics in IVD Testing Market: https://www.towardshealthcare.com/insights/bioinformatics-in-ivd-testing-market-sizing
About Towards Healthcare
Towards Healthcare is a healthcare-focused research and consulting firm that publishes market research reports, news and industry insights across pharmaceuticals, biotechnology, diagnostics, medical devices, healthcare IT, life sciences and cell and gene therapies. Its offerings include healthcare and cell and gene therapy intelligence platforms, an access dashboard and customized research for decision-makers. Website: https://www.towardshealthcare.com/
Our Partners
- Precedence Research: https://www.precedenceresearch.com/
- Towards Packaging: https://www.towardspackaging.com/
- Towards Chemical & Materials: https://www.towardschemandmaterials.com/
Connect With Us
- USA: +1 804 441 9344
- APAC: +61 485 981 310 or +91 87933 22019
- Singapore: +65 3105 1271
- Europe: +44 7383 092 044
- Email: sales@towardshealthcare.com
Social Media
Comments (0)
Login to join the conversation
Login / RegisterNo comments yet. Be the first to comment!